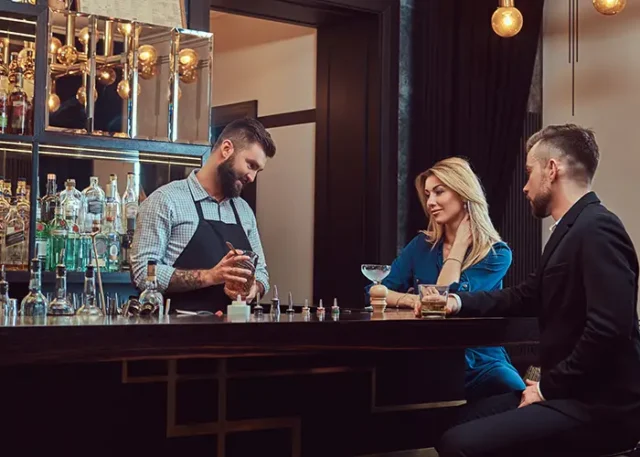
At ten to midnight on a Friday in October 2026, a couple from Boston squeezed up to the bar of a pub near Dublin’s Temple Bar and asked to start a tab. The bartender took their credit card, tapped it on a terminal, then slid it into a pint glass behind the till with a dozen others. By the time they left, two hours and five rounds later, their banking app showed two separate amounts from the same pub. Neither of them had expected that.
Running a tab is one of the easiest ways to drink with friends abroad, and also one of the most confusing to see afterward on a statement. Bars in different countries handle tabs differently. Some keep the card, some only record it, and almost all of them place a temporary hold on it first (often without saying so). For American travelers, that hold, combined with currency prompts and foreign transaction fees, can make a simple night out look a lot more expensive than it was.
Once the last guest has left, attention shifts to balancing the day’s takings, a routine that restaurant ePOS solutions like Tableview.com help simplify by bringing sales records, payment transactions, and end-of-day reporting into one workflow. For guests, that end-of-night routine matters because it’s often when an open tab gets closed and the final charge on a card is settled.
How a Bar Tab Hold Works
When a bar opens a tab, it usually runs a pre-authorization on the card. That’s a request to the card issuer to reserve a set amount, often somewhere around the price of a few rounds, to make sure the card is good before any drinks are poured. Nothing has been charged yet. When the tab is closed, the bar’s POS system for bar and restaurant service sends the final amount, and that’s what gets charged. The original hold is supposed to drop away once the final charge goes through. In practice, depending on the bank, it can sit on an account as a pending item for several business days. On a credit card, that only reduces available credit for a while. On a debit card, it ties up real money from your checking account.
A few practical points follow from that.
- Use a credit card rather than a debit card to open tabs abroad
- Ask how much the bar holds when opening a tab, so the pending amount doesn’t come as a surprise
- Expect the pending hold to disappear within a few business days, and call the bank if it hasn’t after a week
Why It Looks Like You Paid Twice
On a Saturday in October 2026, a traveler from Denver spent an evening in Lisbon’s Bairro Alto with three friends from a walking tour. The first bar opened a tab on her debit card and placed a €150 hold. The final bill came to €62.80, which she paid on the same card when the group moved on. By the next morning, her banking app showed both amounts, and her available balance was more than €200 lower than she’d expected. Her card was then declined for a €75 hotel incidentals deposit at check-in that afternoon in Sintra. She spent forty minutes on the phone to her bank from the hotel lobby, and was told the hold would drop off automatically within a few days. It did, four business days later, but she had to use a friend’s card for the deposit in the meantime.
The bar did nothing unusual.
Holds like that are normal practice, and on a credit card they would barely have been noticed. The problem came from using a debit card on a trip where several holds and deposits stacked up within a single weekend. Hotels do the same thing at check-in, so a run of tabs and hotel stays can tie up a surprising amount of a checking account at once.
Currency at the End of the Night
Closing a tab abroad usually means one more screen on the terminal. Many card readers offer to charge in dollars instead of euros or pounds, a choice known as dynamic currency conversion. Picking means the bar’s payment provider sets the exchange rate, usually with a built-in markup; choosing the local currency lets your own card issuer handle the conversion, which is usually cheaper. Modern ePOS for hospitality shows the choice automatically for foreign cards, and late at night, in a busy bar, it’s easy to press the wrong button.
- Always choose the local currency when the terminal asks
- Check whether your card charges a foreign transaction fee, since a 3 percent fee on every tab adds up over a long trip
When the Bar Is Also a Restaurant
Plenty of bars abroad serve food, and in Spain, Portugal and Ireland the line between a bar and a restaurant is often blurry. Where a venue runs a restaurant ePOS system for both, a tab can cover drinks at the counter and dinner at a table, all closed out together at the end. That’s convenient, but it also means the hold placed at the start of the night may be well below the final bill, and some venues will ask to run a second authorization partway through. Small detail, but worth knowing. One quirk in Spain catches visitors out too. Many bars charge more for the same drink at a table on the terrace than at the counter, and the difference shows up on the final bill.
Hotel bars work a little differently again. They often charge drinks to the room instead of opening a card tab, and the ePOS system for restaurant and bar service passes those charges to the front desk for payment at checkout. Check the room bill carefully, since a tab charged to the wrong room number is one of the more common mistakes at busy hotel bars.
Before Opening a Tab
Venue owners compare the best ePOS systems for restaurants and bars on speed and reporting. For travelers, the question is simpler: how does this bar handle your card?
- Ask whether the bar will keep your physical card, and keep it with you if you can.
- Pay per round instead of opening a tab if you’re only staying for one or two drinks.
- Close your tab yourself before leaving, because some bars close forgotten tabs at the end of the night and may add a service charge when they do
- Take a photo of the final receipt.
- Watch your banking app the next morning for any pending hold that looks larger than expected.d
Before your next night out abroad, put a credit card with no foreign transaction fees at the front of your wallet and keep the debit card for ATM withdrawals.